Daily Spend Planner: Track Expenses and Spot Patterns
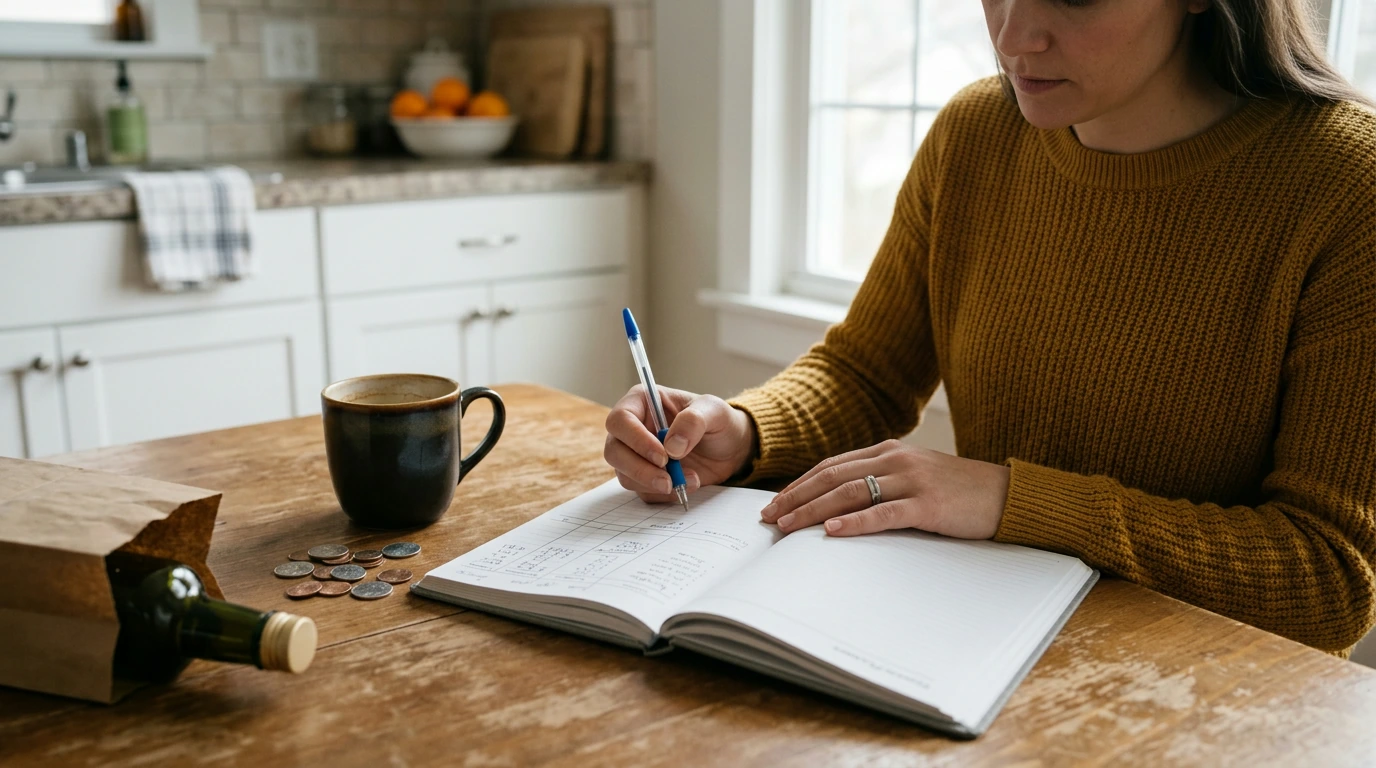
A coffee on the way to work, a quick grocery stop, or a parking fee may not seem like much on its own. Over a week, though, everyday purchases can add up in ways that are easy to miss. Taking a few minutes to record them can give you a clearer starting point for deciding how you want to use your money. For more guidance, see What You Spend – Spend Smart Eat Smart – Iowa State University.
Our Daily Spend Planner offers a way to build that habit into your routine. You don’t need a perfect system or a major financial overhaul to begin. Start with the purchases you can remember, keep your notes practical, and use what you learn to make decisions that fit your life. For further reading, see Home Budget Calculator.
Make Daily Spending Easier to See
Small purchases often happen between larger financial decisions. You might remember your rent payment but forget several convenience-store visits or delivery fees. Recording those expenses puts them in the same picture as the purchases you already notice.
For example, tracking your afternoon snacks for a week might show that you spend more on them than you expected. That doesn’t mean you have to stop buying them. It gives you a chance to decide whether the convenience is worth the cost or whether you would rather use some of that money elsewhere.
Our Daily Spend Planner is in stock and listed at $21.99. It’s an option if you want a dedicated place to make spending checks part of your day. The goal is not to judge every purchase, but to notice patterns with enough detail to make informed choices.
Start a Simple Spending Routine
Choose a regular moment when recording expenses feels natural. You could make a note after shopping, review purchases during an evening break, or set aside a few minutes before bed. Connecting the task to something you already do can make it easier to remember.
For each expense, note the amount and what it was for. You might write “$12 lunch” or “$35 gas,” adding a date or payment method if that helps you. If you share some costs with someone else, decide whether you want to record the full amount or only your share, and use that approach consistently.
Keep the routine manageable. You don’t need to sort every purchase into a detailed category immediately. A short note is useful even if you organize it later. If you forget to record something, pick up where you left off rather than waiting for a new week or month to start.
You can also decide how to handle cash purchases and automatic payments. Including both can make your picture more complete, but starting with one group of expenses is reasonable if tracking everything at once feels overwhelming.
Turn Daily Entries Into Useful Insights
Once a week, look back at your entries and group them into categories that make sense for you. Food, transportation, household supplies, and entertainment are common starting points. Your categories can be broad; the point is to make the totals easy to understand.
The table below is an illustrative weekly check, not a description of the planner’s layout. Your categories, amounts, and next steps will depend on your own circumstances.
| Category | Example spending | Possible next step |
|---|---|---|
| Food and drinks | $45 | Set a comfortable limit for the coming week |
| Transport | $30 | Compare the total with upcoming travel needs |
| Entertainment | $25 | Decide which activities are worth keeping |
Look for a pattern rather than a single purchase to criticize. If food spending is higher than you expected, you might plan one more meal at home. If transportation costs vary, you might set aside a little more for a week with extra travel. Choose one realistic adjustment and see how it works before adding another.
Spending records can also inform a broader budget. Compare what you record with your income, recurring bills, savings goals, and other priorities. The Consumer Financial Protection Bureau’s budgeting resources offer additional tools for thinking through income and expenses.
Fit Spending Checks Into Your Life
Missed days happen. If you fall behind, use receipts, bank transactions, or payment-app records to fill in what you reasonably can. You can also leave a gap and resume today. An imperfect record is still a useful starting point, and catching up shouldn’t become a task so large that you abandon the habit.
During your weekly review, look ahead as well as back. A birthday, a trip, or a recurring bill may affect what you need in the coming weeks. Noting those expenses early gives you time to consider how they fit alongside everyday purchases.
For seasonal costs, our in-stock The Year of Holidays Planner is another option to explore alongside your regular spending routine. You can use your daily records to consider how much room you have for upcoming celebrations without losing sight of routine expenses.
Start with a few minutes a day and let the routine grow with your needs. Our team invites you to explore the Daily Spend Planner and choose a spending check-in you can return to week after week.
FAQ
How often should I review my spending?
Record expenses regularly and review the bigger picture weekly. Choose a schedule you can sustain, even if that means starting with a shorter check-in.
Can a daily spend planner help me make a budget?
Yes. Spending records can show where your money goes and help inform a budget, but you still need to make decisions about your income, bills, and priorities.
What if I miss a day of tracking?
Check available receipts or transaction records and fill in what is practical. Then resume your routine without worrying about making the record perfect.



Leave a comment